

Best Paying Accident Plans for Martial Artists for 2027 – State by State
Our 2027 ranking of high-paying, low-cost accident plans for martial artists and BJJ students, how to stack them, and which are available in your state.
Covering The Mats Blog · JiuJitsuInsurance.com
Every academy has the same story on repeat: someone posts on a bad arm, gets stacked in a scramble, or catches a heel hook a beat too late, and suddenly they're in the ER instead of at open mat. The injury heals. The bills and missed work are what linger. This guide is our 2027 ranking of the highest-paying, low-cost accident plans that martial artists can buy on their own or stack together, plus a state-by-state map so you can see what's likely available where you train.
These are 24-hour injury plans. They don't just cover jiu-jitsu. They cover accidental injuries on and off the mats, at work, at home, or out on the weekend. What makes them different is that they don't exclude jiu-jitsu or other martial arts training, and that's exactly why we call it Jiu-Jitsu Insurance.
On the job vs. off the job: The Washington National accident plans cover injuries whether they happen on the job or off. The Companion Life Flex plan does not pay for work injuries that are covered by workers' compensation, so it's best for injuries off the clock, like training, sports and everyday life. Pairing Flex with a Washington National plan helps fill that gap.
Availability varies by state. Benefits, prices, availability and exclusions vary by state, age, plan design and benefit level, and they can change. Use this guide as a starting point, then confirm with your broker.
The 2027 ranking: highest potential payout
We ranked these plans by potential payout on a covered injury, with monthly prices that keep them within reach for most students, coaches and competitors. Prices are estimates for illustration only.
1. Companion Life – Flex Plan (accident medical expense)
- How it pays: Reimburses actual covered accident medical bills, after a deductible, up to a yearly maximum. It's an excess plan, so it pays after any health insurance you have, or first if you don't have any.
- Why it ranks #1: It can be designed with up to a $30,000 yearly maximum, the biggest potential payout on this list for a serious injury with surgery, imaging and lots of PT.
- Estimated cost: roughly $25–$29/month for a $30,000 accident-only design (an estimate that varies by state, age and plan design).
- Watch for: In the version we reviewed, ER care may be covered only when followed by a hospital admission. If you're treated in the ER and released, ask how ER visits are handled in your state.
2. Washington National – Accident Plan (A4)
- How it pays: Fixed cash (indemnity) for covered events like fractures, dislocations, ER visits, imaging, physician visits and physical therapy. It's paid directly to you, regardless of other insurance.
- Why it ranks #2: Several benefit levels, with the higher levels paying meaningful cash for the injuries we see most on the mats.
- Estimated cost: about $35/month.
3. Washington National – Accident Assure Plan (A3)
- How it pays: Fixed cash per covered event, much like A4, paid regardless of other coverage.
- Why it ranks #3: Solid scheduled benefits for fractures, dislocations, ER and therapy. It's offered in a smaller group of states and is often the Washington National option where A4 isn't available.
- Estimated cost: about $35/month.
4. AFLAC – Tier One Accident
- How it pays: Fixed cash for covered accident treatment, fractures, dislocations, concussion, imaging, follow-up care and therapy, paid regardless of other coverage.
- Why it's on the list: It's widely available, and it's a strong option for competitors (more on that below).
- Estimated cost: about $36/month.
Monthly prices are estimates only and vary by state, age, plan design and benefit level. Your actual premium comes from your quote.
Are martial arts covered?
This is the question we get most, so here it is plainly. Based on the sample materials we reviewed, these plans do not exclude recreational martial arts (jiu-jitsu, judo, wrestling, kickboxing, Muay Thai and the like) as long as you're not paid to compete. The Companion Life and Washington National materials we reviewed exclude professional, semi-pro or paid competition and events for pay or prize money. Flex's sample certificate also excludes intercollegiate sports.
If you compete for pay or prize money, AFLAC is the plan to look at. The sample AFLAC policy we reviewed has no general sports exclusion. It even adds a bonus benefit for injuries in organized amateur competition or supervised practice for it, though that bonus doesn't apply to paid competition. Wording varies by state, so confirm with your broker how your state's plan treats your situation, especially if you fight for purses, coach for pay or compete in professional events.
How stacking works
Here's the fun part: you don't have to pick just one. You can generally hold up to three of these plans at once:
- Companion Life Flex, which handles the bills,
- plus ONE Washington National plan (A4 or A3), which pays cash,
- plus AFLAC Tier One, which pays more cash.
The two types work differently, and that's why they pair well. Flex reimburses covered medical expenses. The Washington National and AFLAC plans pay fixed cash directly to you, regardless of other insurance. You can use that cash for deductibles, rent, lost wages, gas to PT or groceries while you heal. (New to these terms? Read our explainer, Reimbursement vs. Indemnity Accident Insurance.)
A hypothetical forearm fracture
Hypothetical illustration, not a quote or guarantee. Bills and benefits are made up for illustration using sample plan materials. Actual benefits vary by state, plan, level and claim review.
A BJJ student with no health insurance fractures a forearm in class. The ER, X-rays, fracture care, an MRI, two ortho follow-ups, six PT sessions and a prescription total $7,550.
- Step 1, Flex only: Flex reimburses $7,300 (bills minus a $250 deductible). Net: –$250 out of pocket. That assumes the ER visit is covered. If it isn't, because of the admission wording, out of pocket is about $3,150.
- Step 2, + AFLAC: about $1,120 in fixed cash. Net: +$870.
- Step 3, + WN A4 (Level 4): about $3,780 in fixed cash. Net: +$4,650 left over for the weeks you're off the mats.
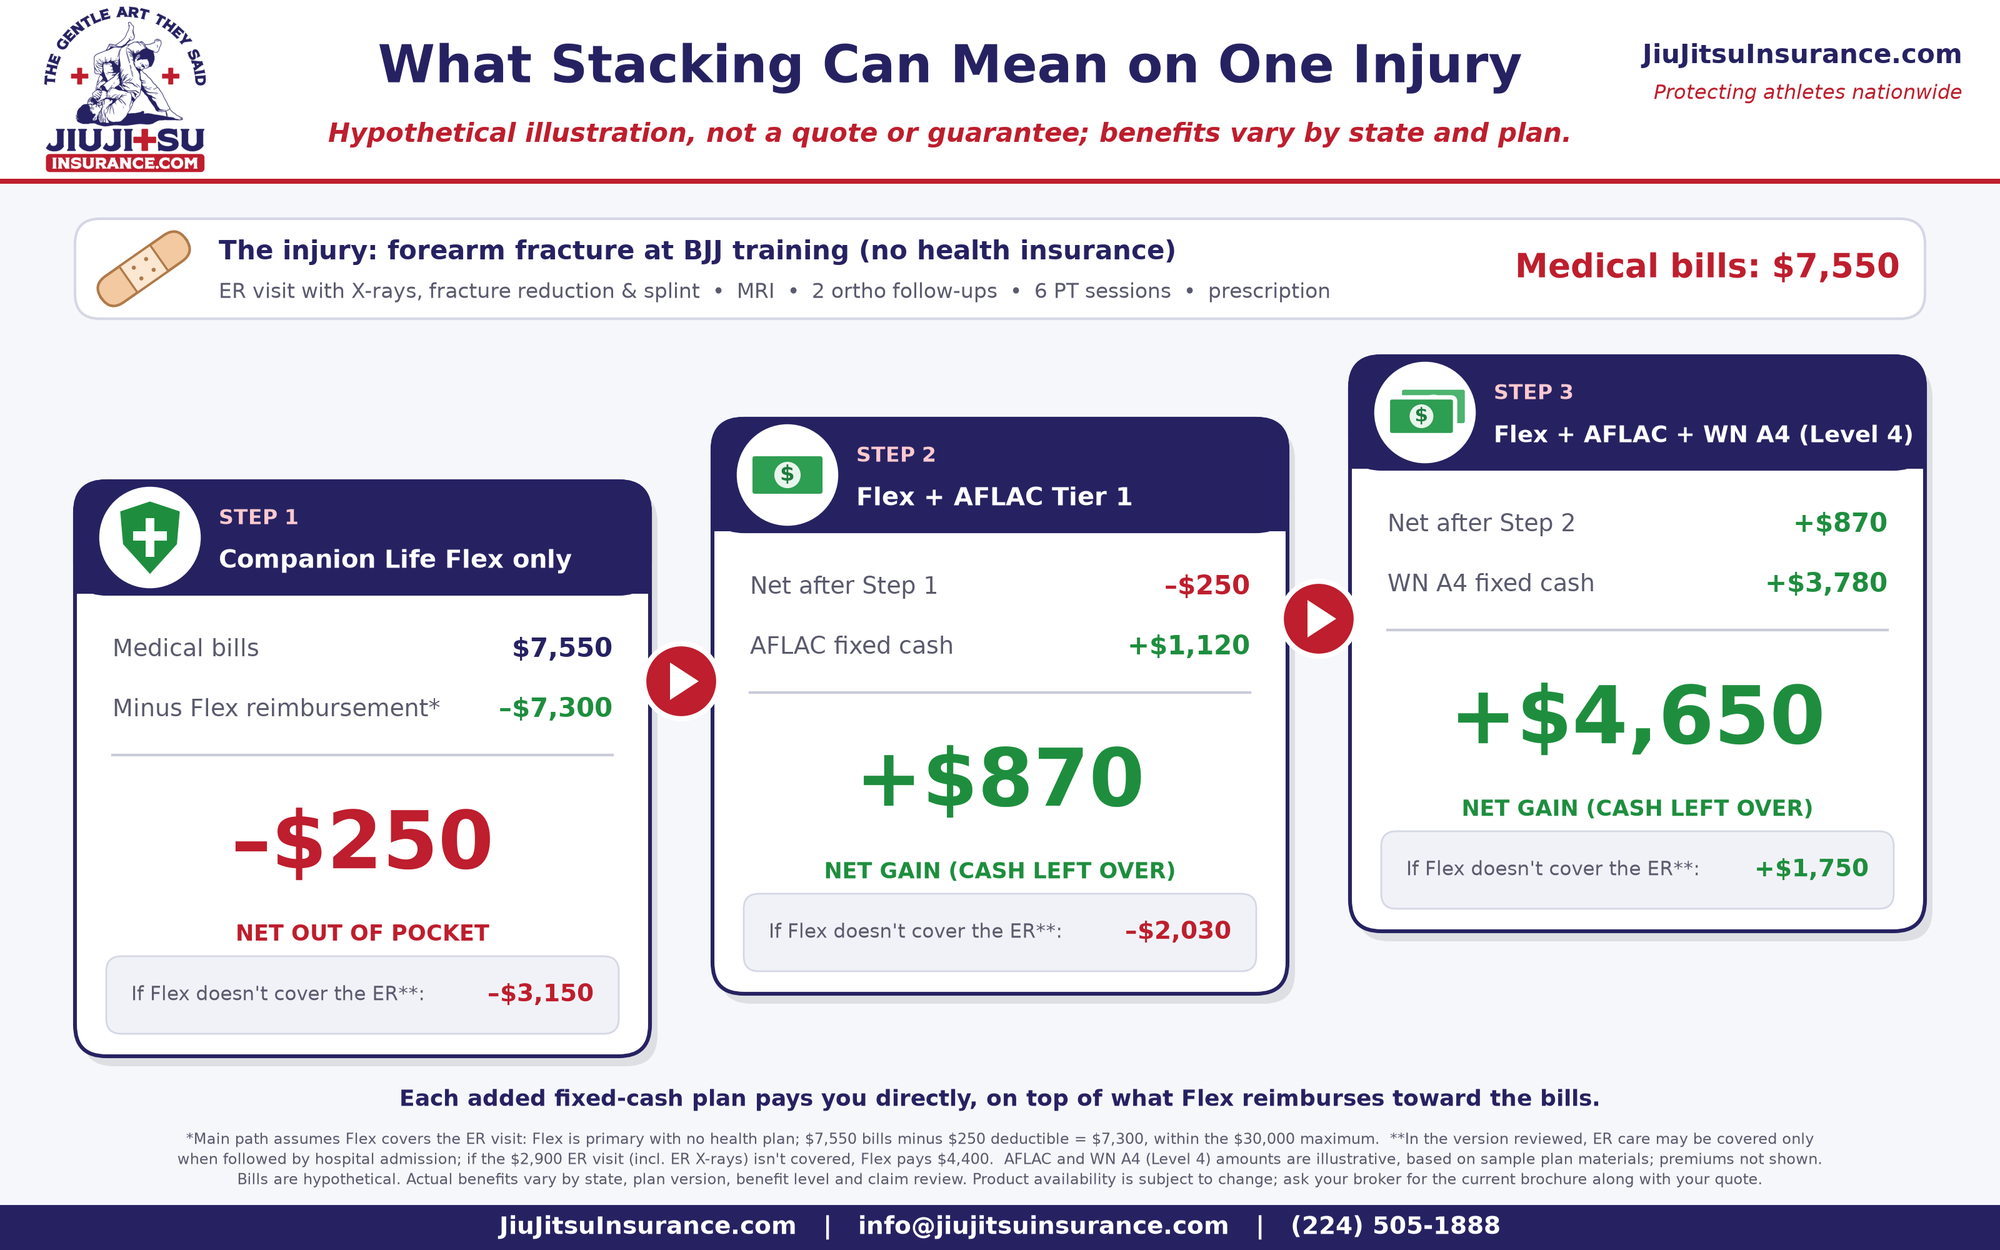
Hypothetical example: how one, two and three stacked plans might pay on a single forearm fracture. If Flex doesn't cover the ER visit, the final result is +$1,750.
State by state: reading the map
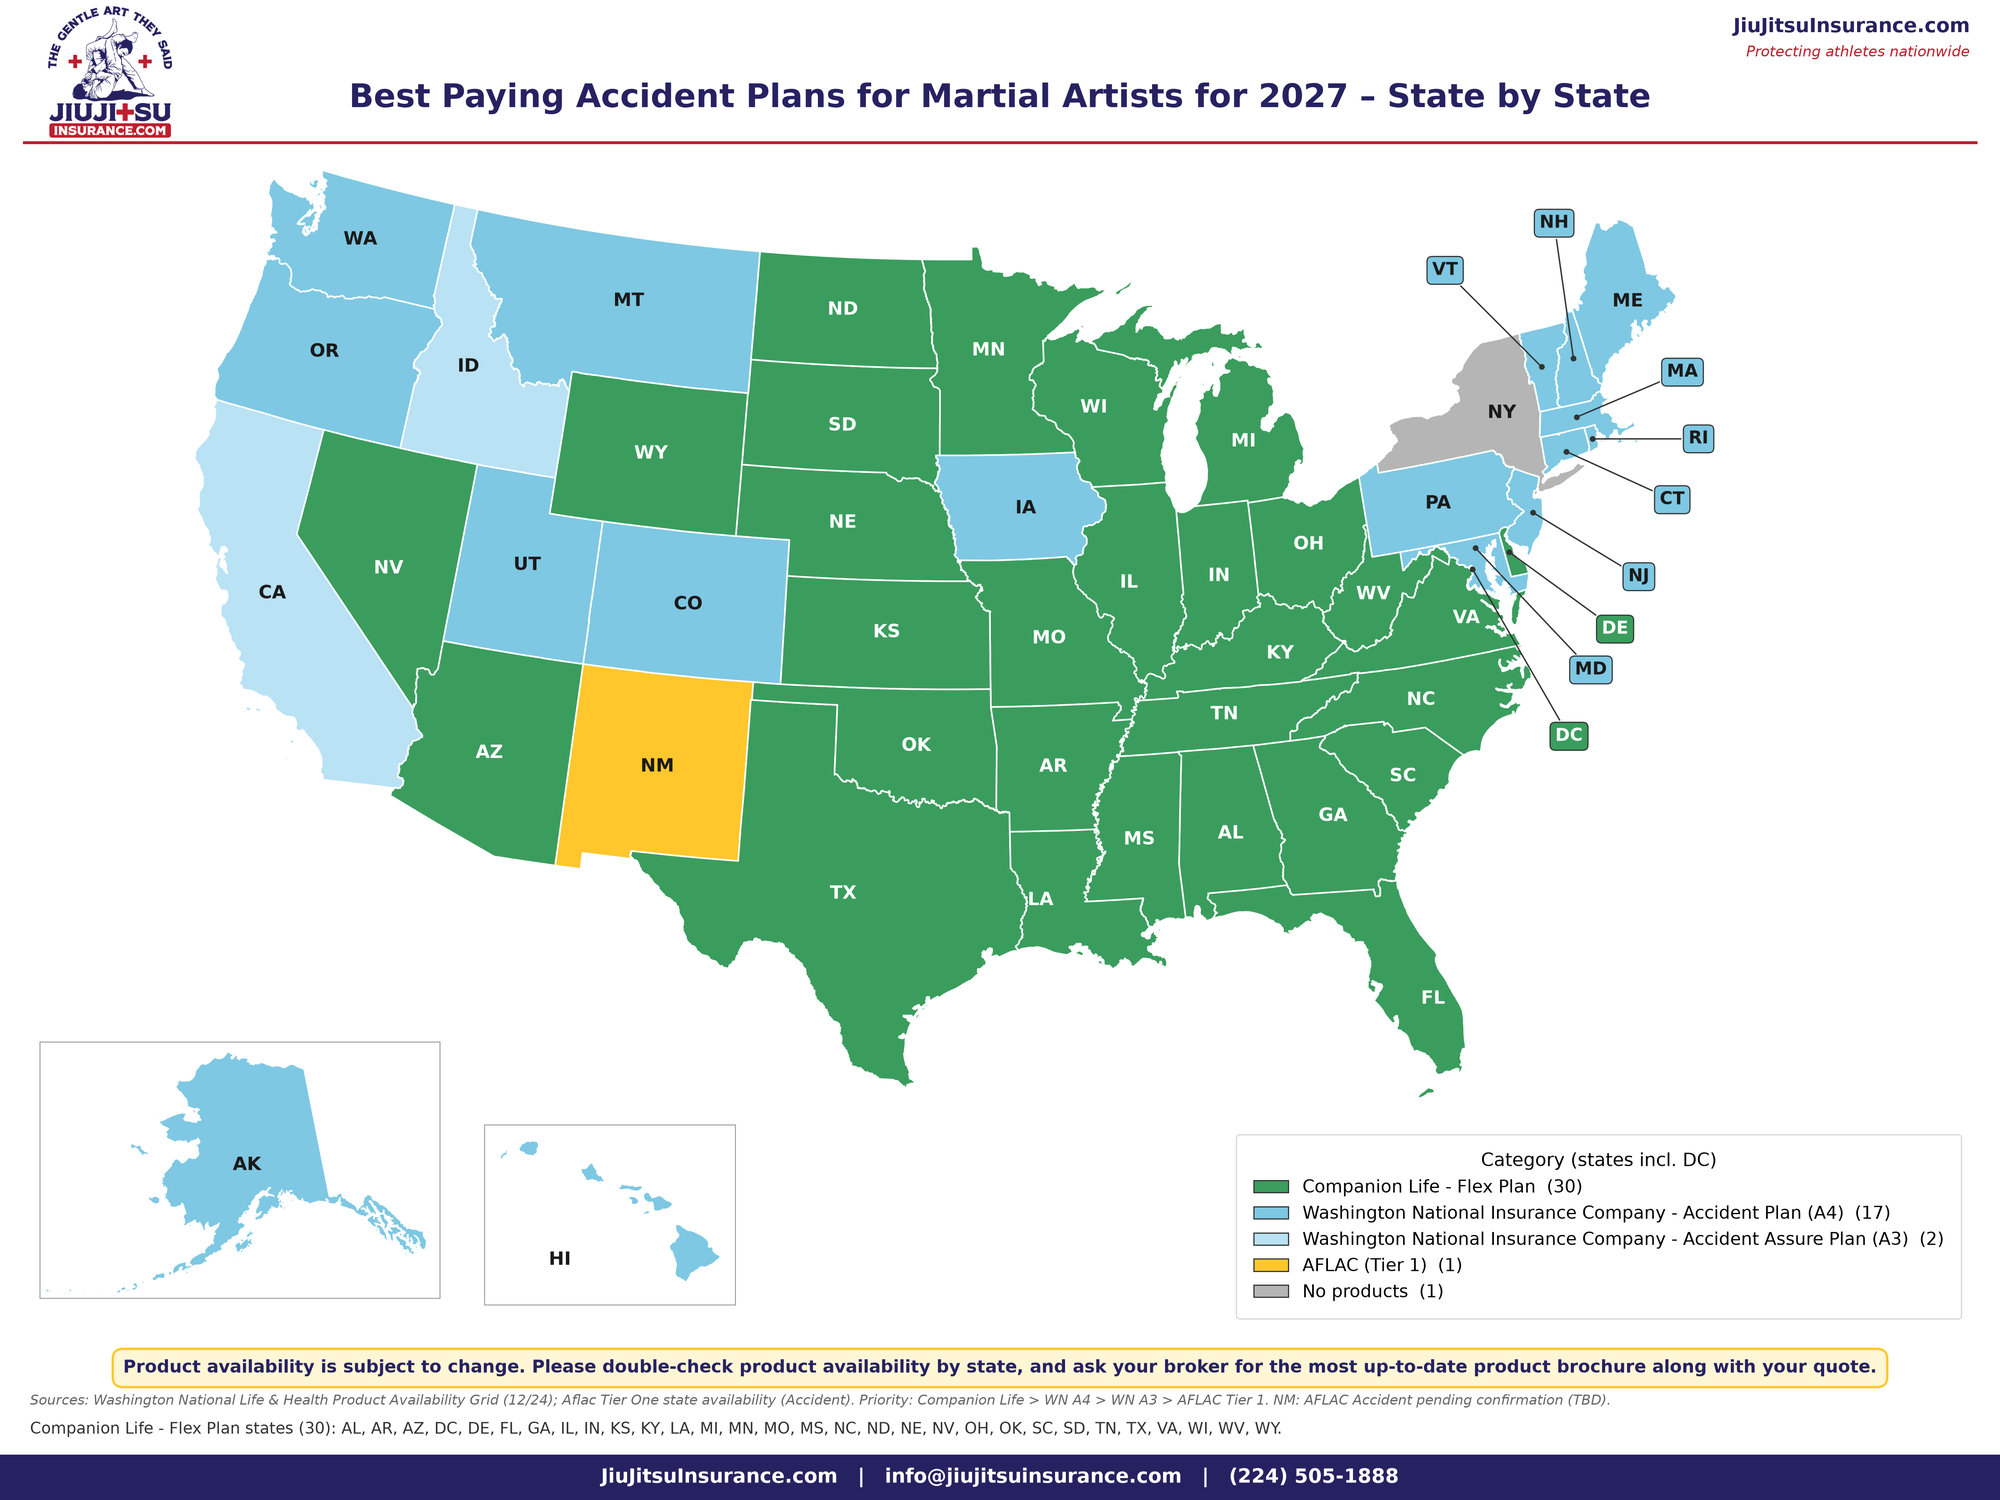
Our 2027 combined map. Each state shows the highest-ranked plan generally available there.
The combined map shows one color per state, following the ranking above. It shows Companion Life Flex where it's available, otherwise Washington National A4, otherwise A3, otherwise AFLAC. Most states have more than one option, so check the individual product maps below to see everything you could stack.
- Companion Life – Flex (30 states plus DC): AL, AR, AZ, DC, DE, FL, GA, IL, IN, KS, KY, LA, MI, MN, MO, MS, NC, ND, NE, NV, OH, OK, SC, SD, TN, TX, VA, WI, WV, WY.
- Washington National – Accident Plan A4 (17 states shown as top pick): AK, CO, CT, HI, IA, MA, MD, ME, MT, NH, NJ, OR, PA, RI, UT, VT, WA.
- Washington National – Accident Assure A3 (2 states shown as top pick): CA, ID. In California, the Washington National accident product may be offered under a different plan name, so ask your broker.
- AFLAC – Tier One: NM, shown as AFLAC for now while availability is pending confirmation.
- No products currently shown: NY.
Individual product maps
Each map shows every state where that product is generally available, regardless of the ranking.
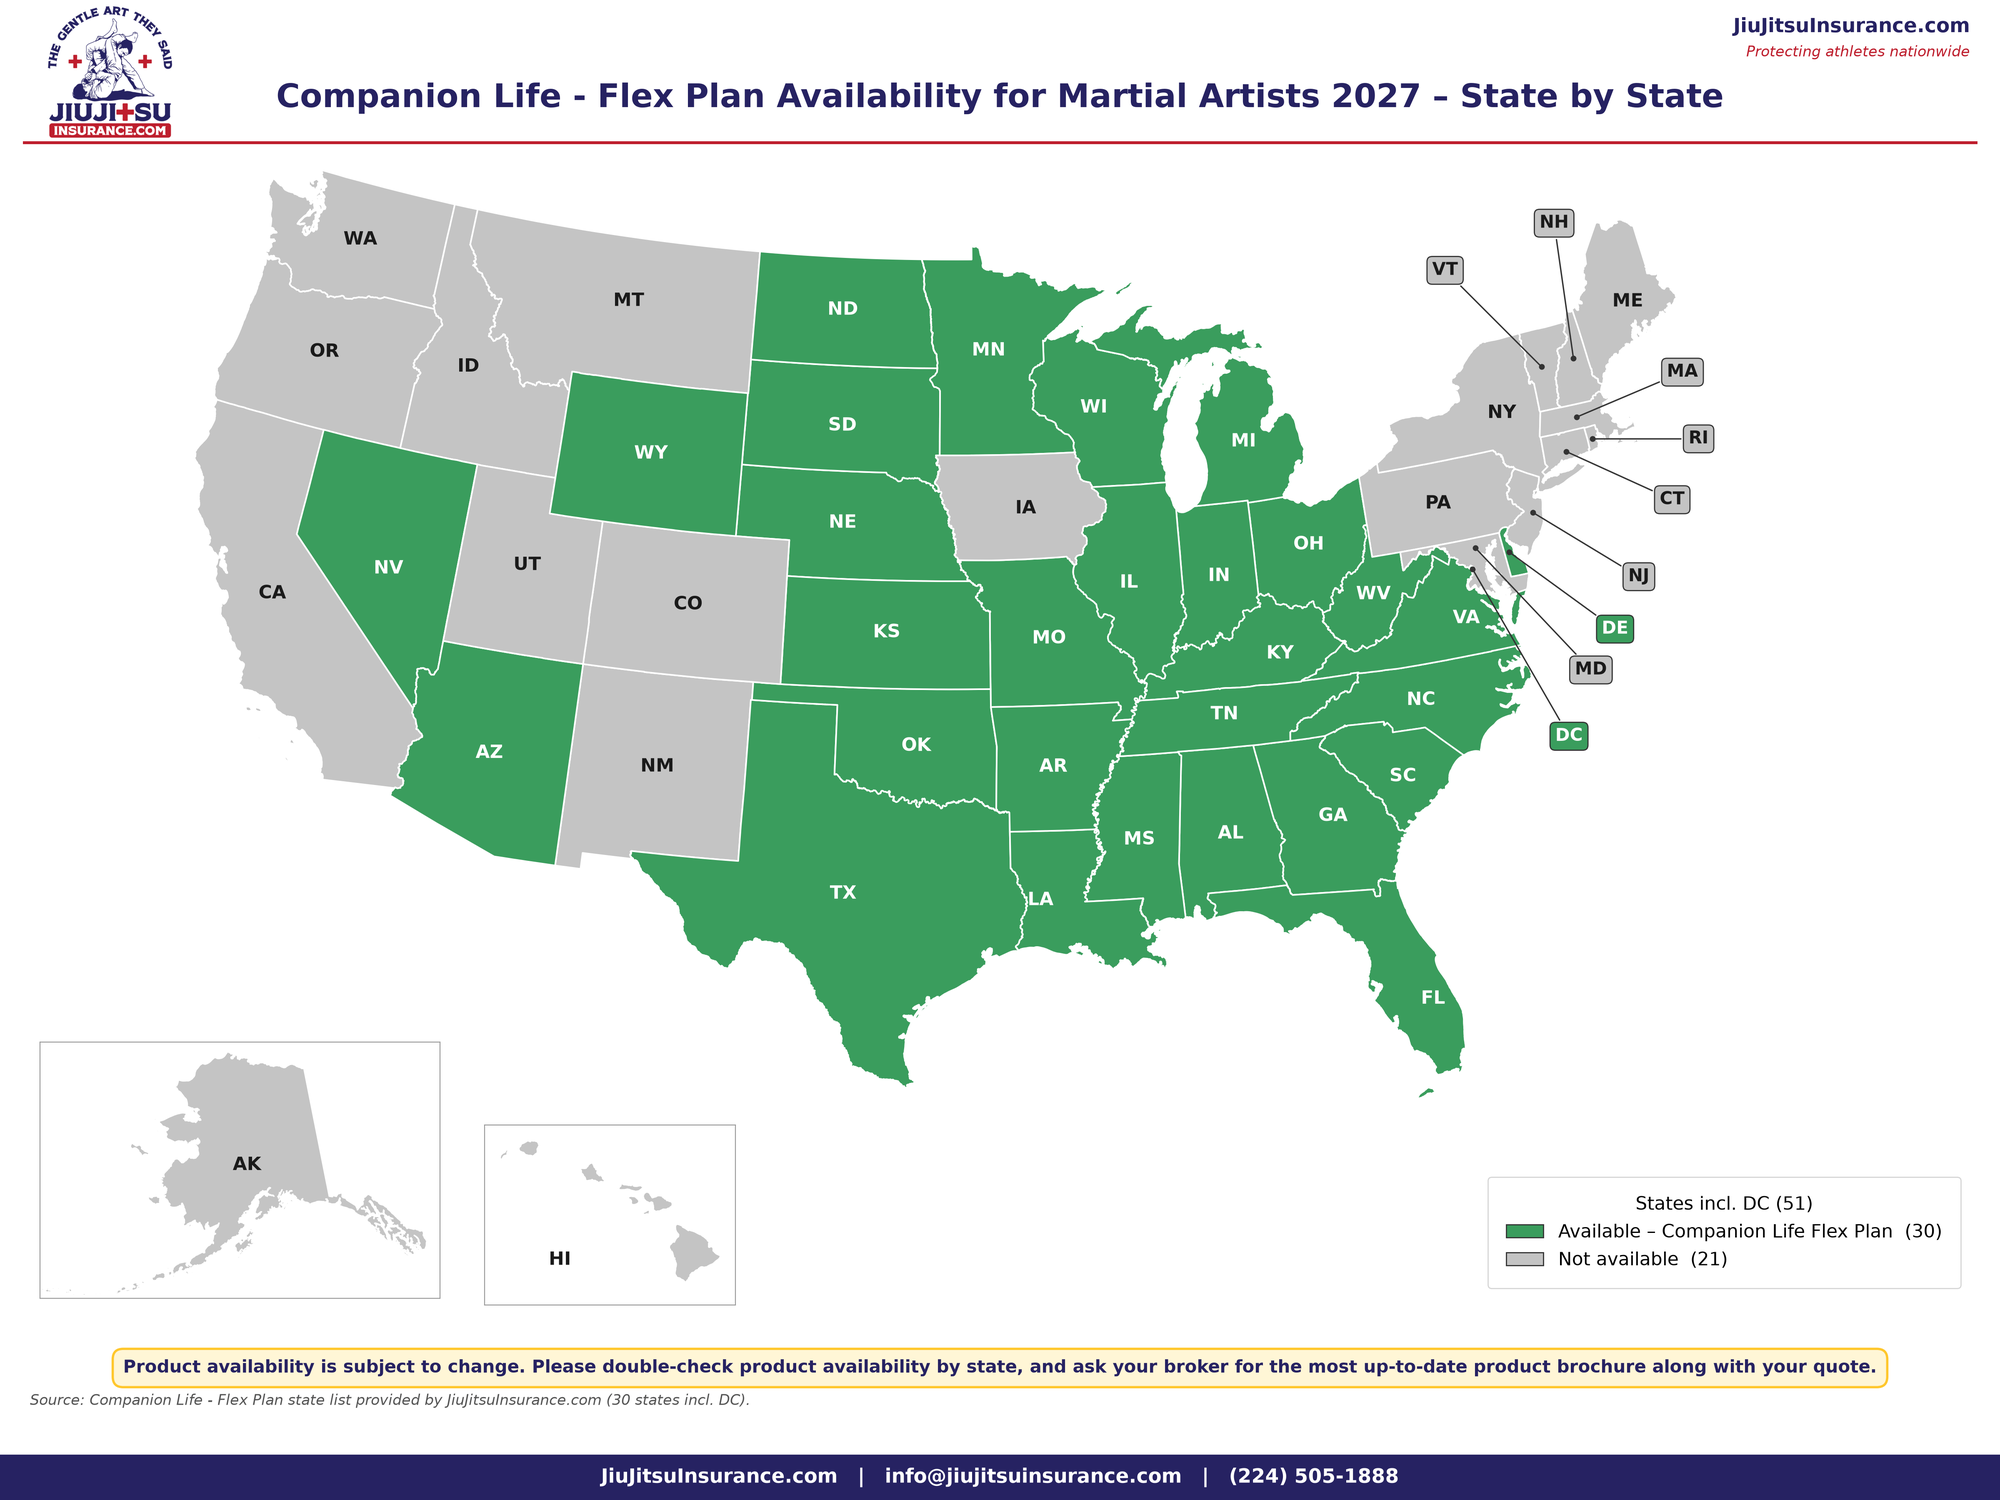
Companion Life – Flex Plan: available in 30 states plus DC (mainly the South and Midwest).
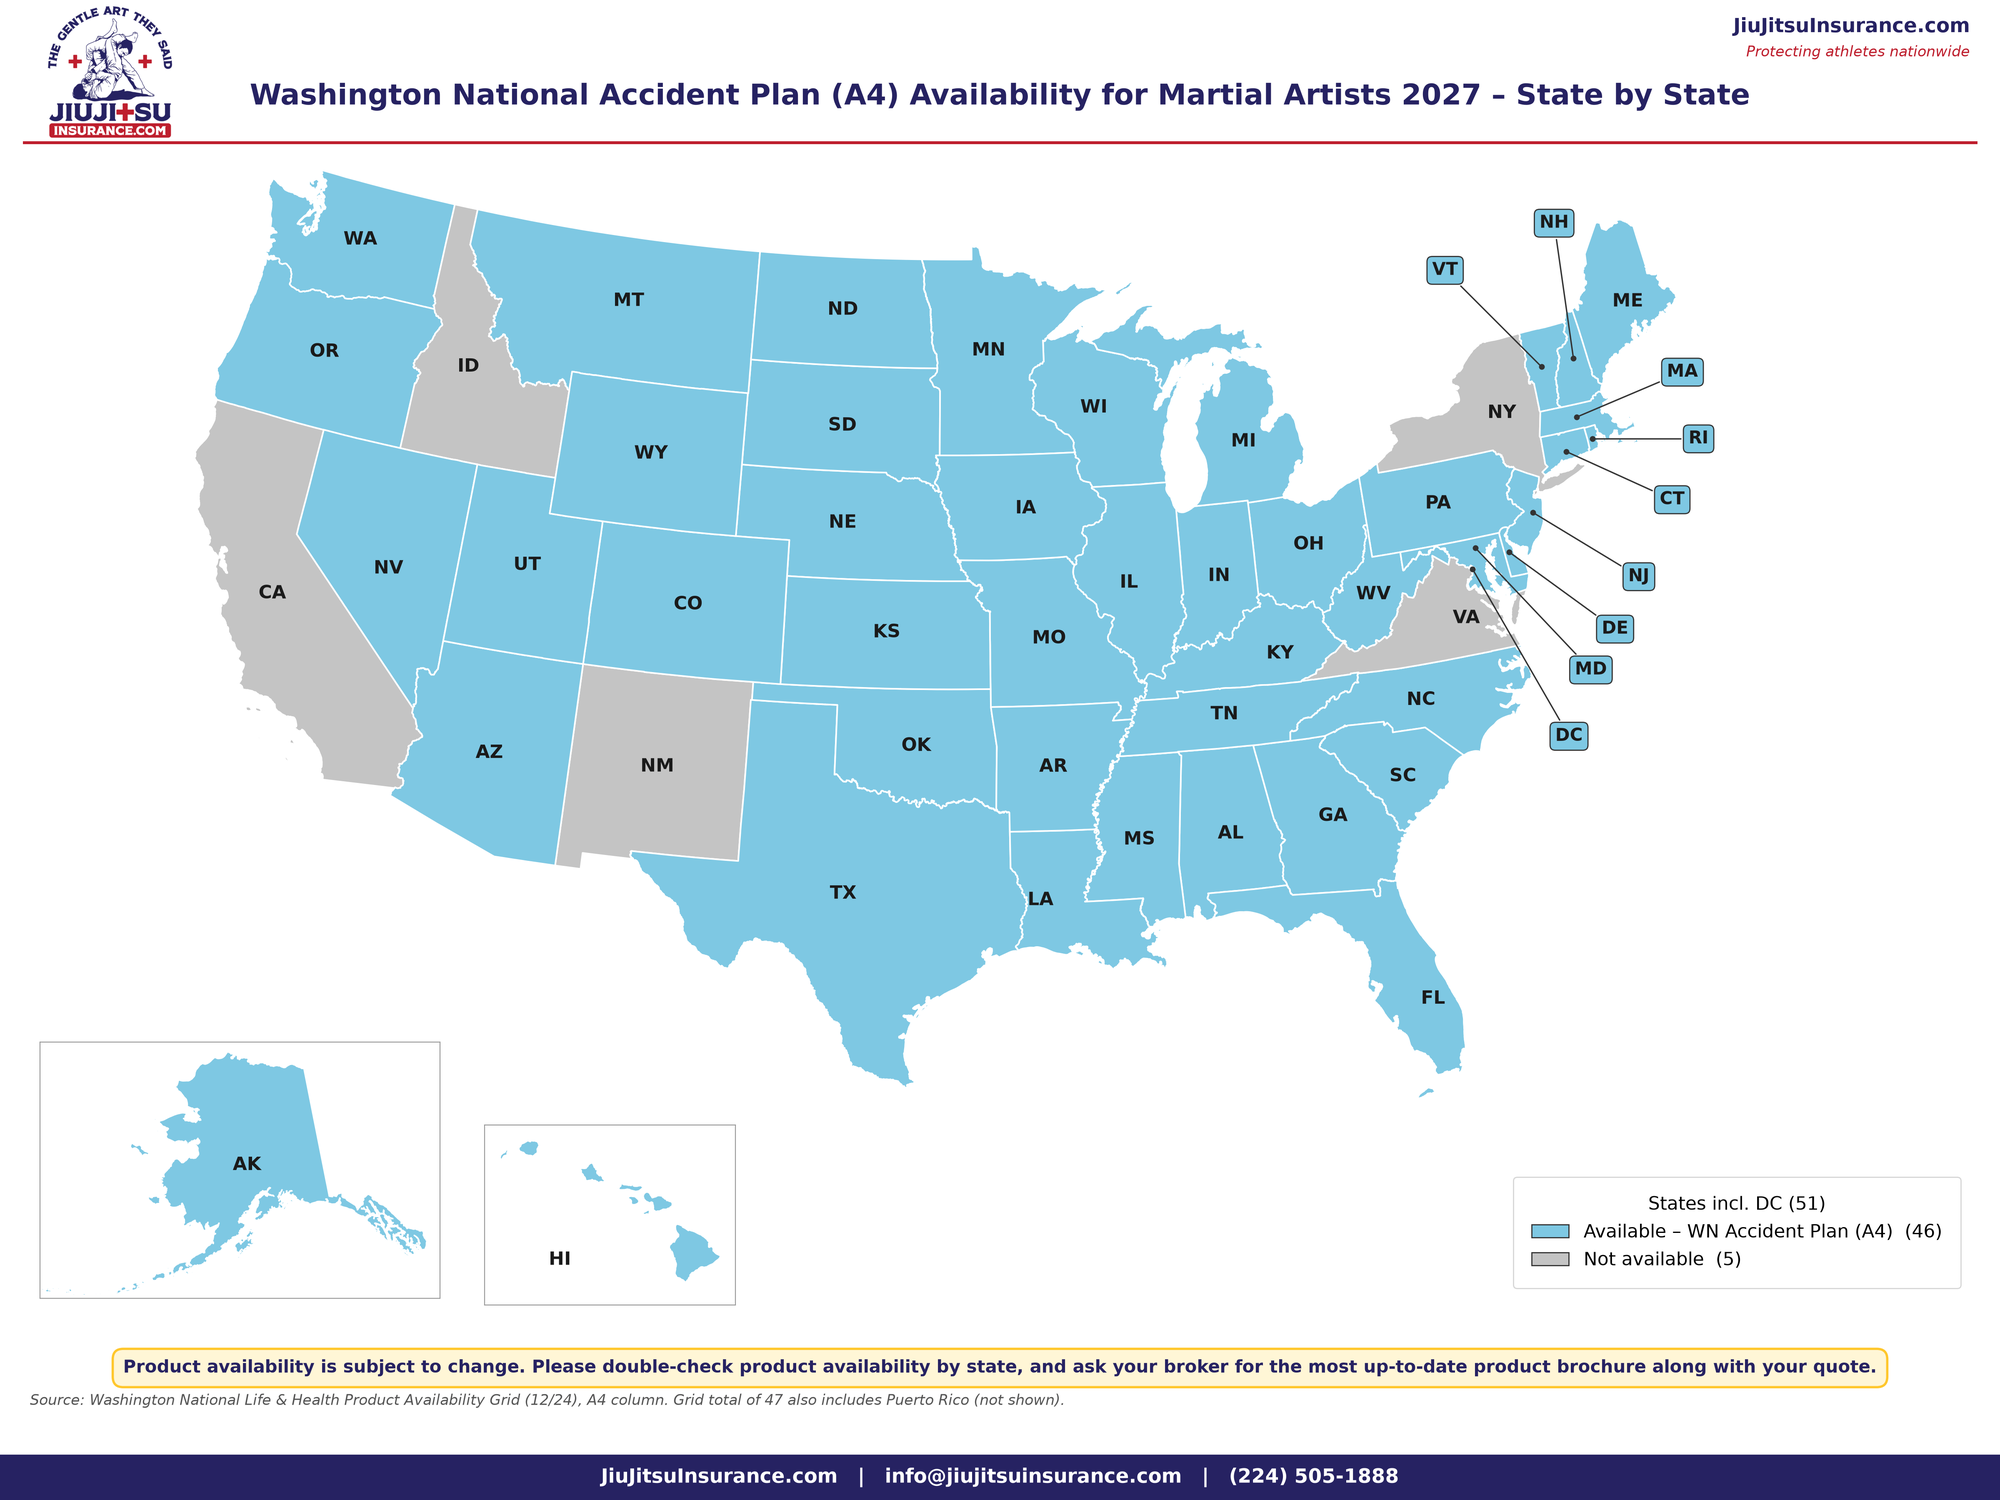
Washington National – Accident Plan (A4): available in most states. Not shown in CA, ID, NM, NY or VA.
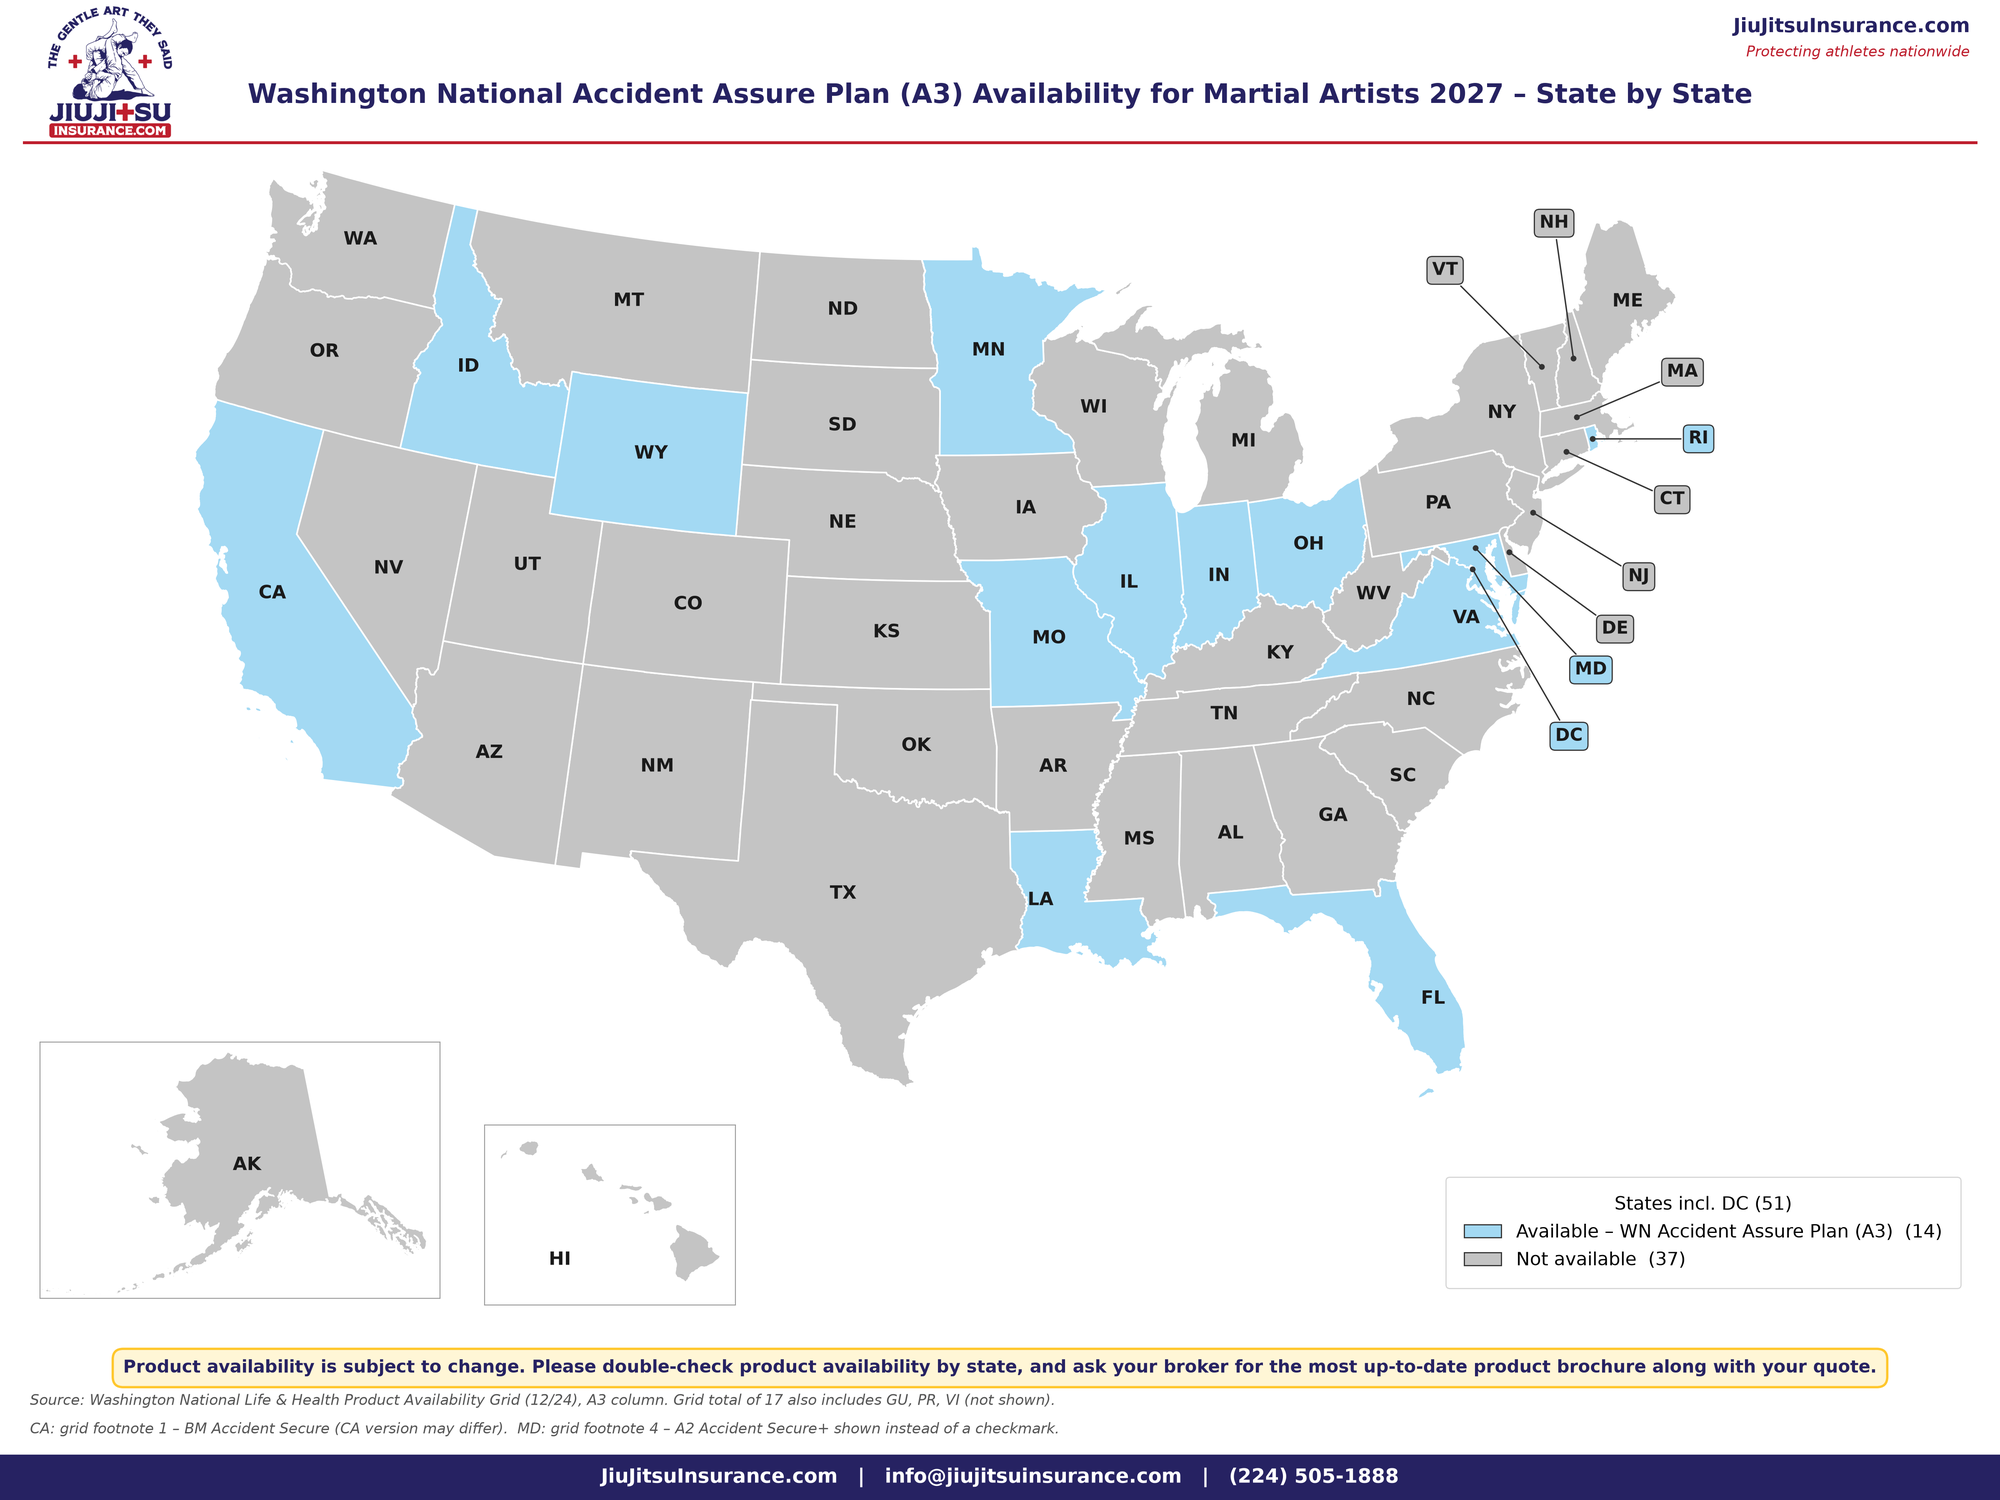
Washington National – Accident Assure (A3): available in a smaller group of states, including CA and ID, where A4 isn't offered.
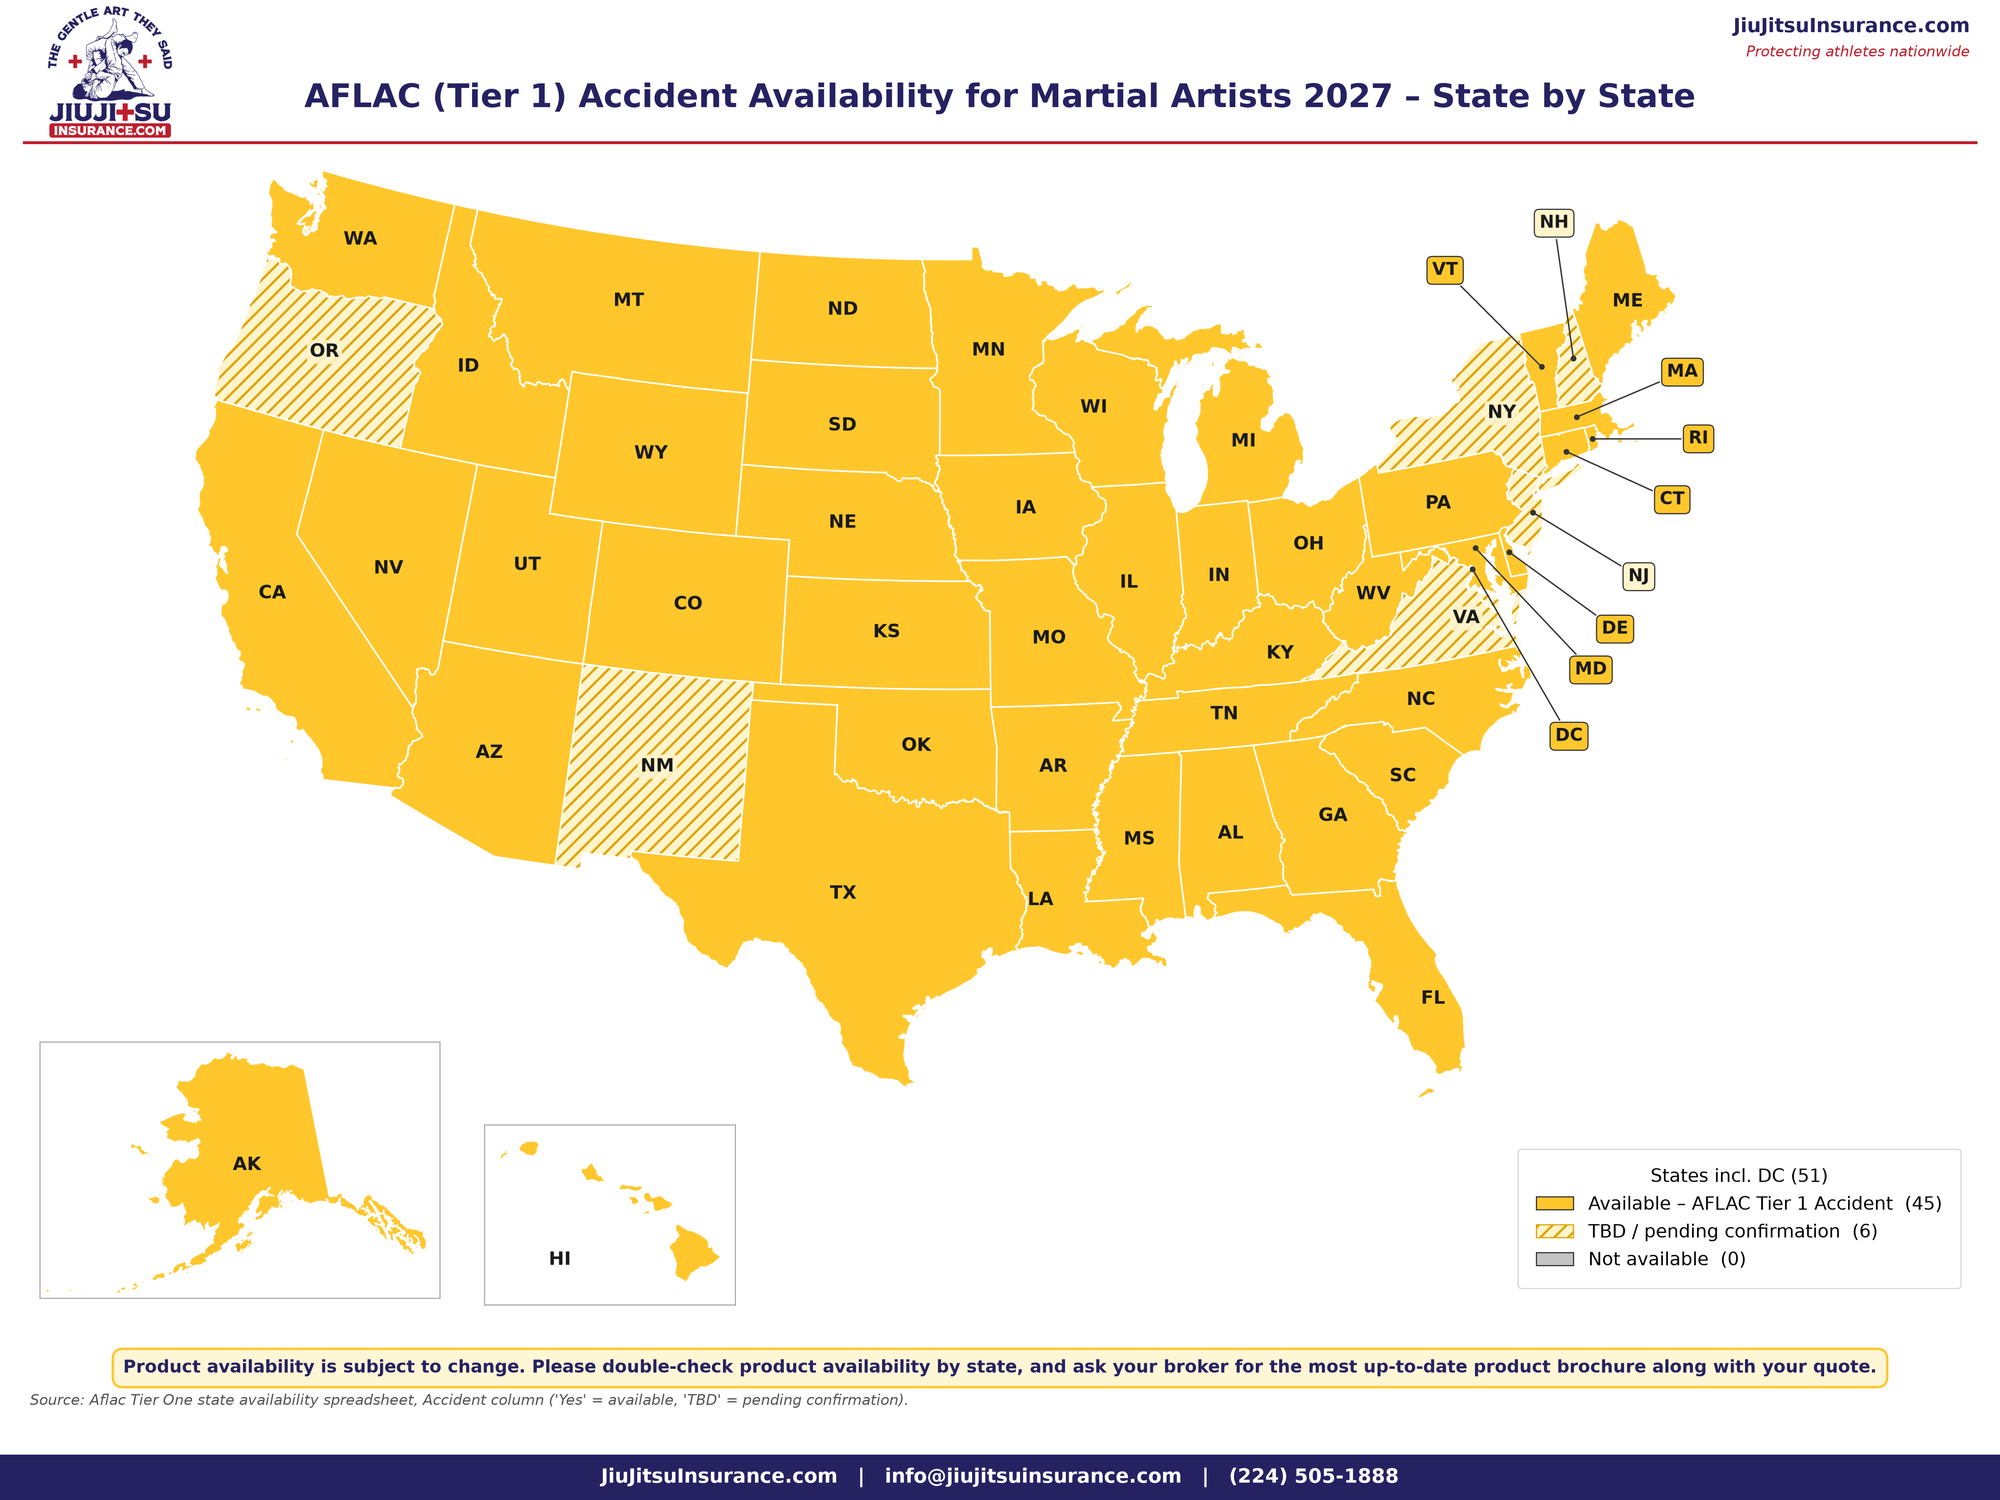
AFLAC – Tier One Accident: widely available. Hatched states (NH, NJ, NM, NY, OR, VA) are pending or to be confirmed.
Quick picks by situation
- You have health insurance with a big deductible: Flex (where available) can help with what your health plan leaves behind, and a cash plan adds money for lost time.
- You don't have health insurance: Flex pays first on accident bills, and stacking a cash plan or two helps cover the gaps. Remember, these are accident-only plans. They don't cover illness.
- You coach, teach or are self-employed: The cash plans (WN and AFLAC) matter most, because they help replace income while you can't work.
- You compete for pay or prizes: Start with AFLAC and confirm the details with your broker.
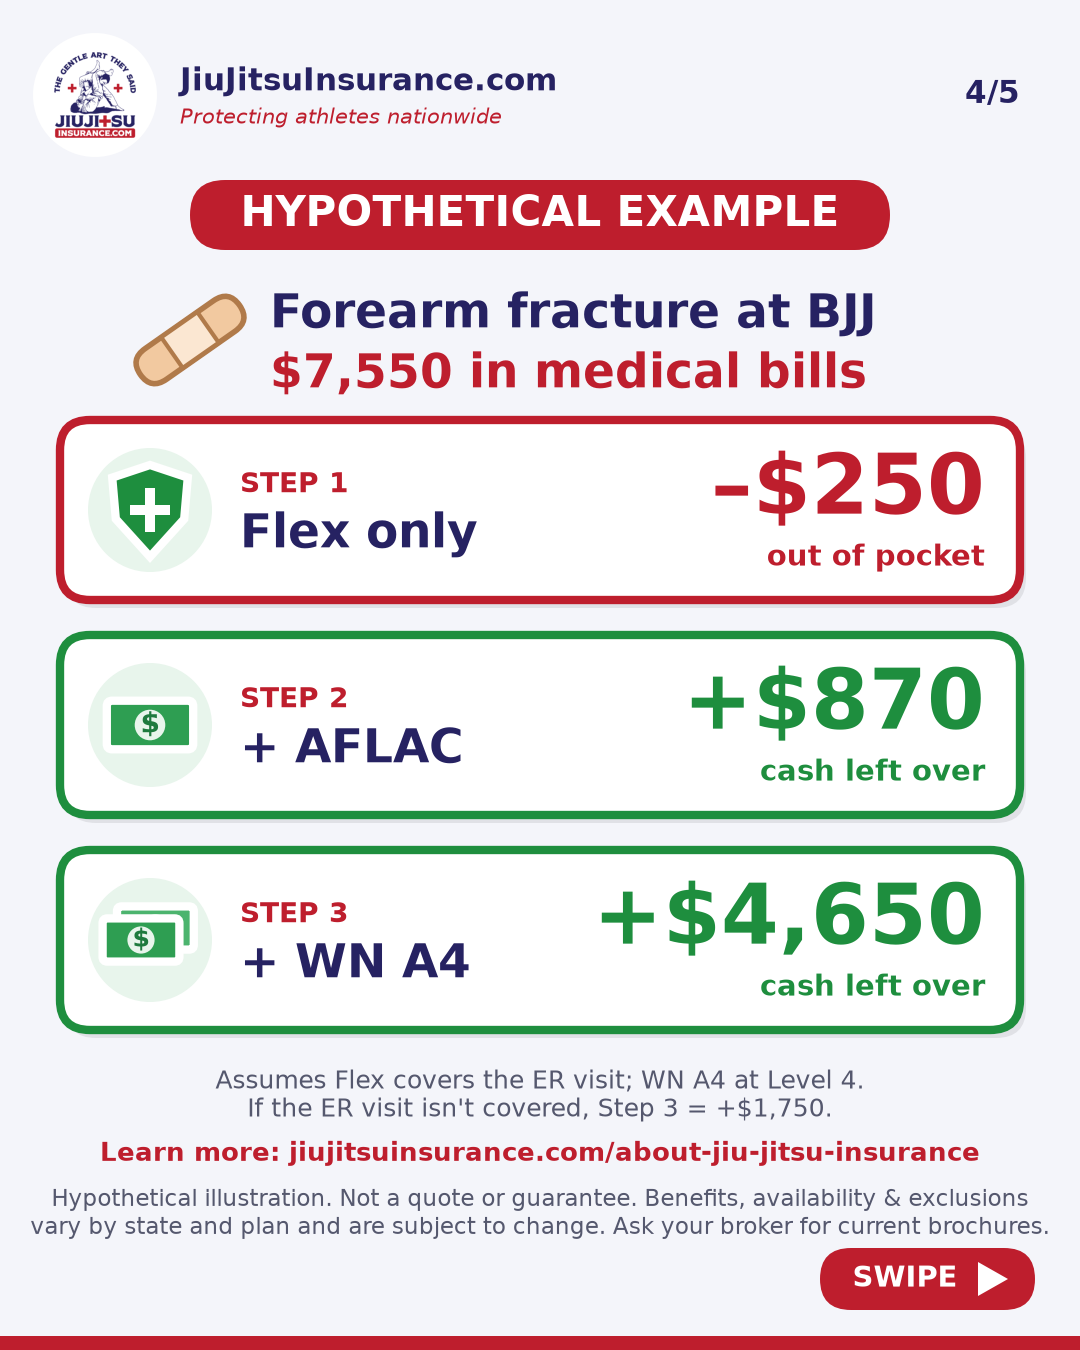
Share it with your team: the stacking example from our Instagram carousel (hypothetical).
FAQ
Can I really have three plans at once? Generally, yes: Companion Life Flex, plus one Washington National plan (A4 or A3), plus AFLAC. They pay in different ways. Owning two similar plans from the same carrier may be limited, so your broker will design the right combination.
Do these plans pay if I have health insurance? Yes. The WN and AFLAC plans pay fixed cash regardless of other coverage. Flex is excess, so it pays after your health plan.
Are tournaments covered? Based on the sample materials we reviewed, amateur competition isn't excluded by name, and AFLAC adds a bonus for organized amateur events. Paid competition is typically excluded under Flex and the WN plans. Confirm with your broker.
How accurate are the prices? They're estimates for illustration. Your premium depends on your state, age, plan design and benefit level.
What if my state isn't shown for a plan? Availability changes. Ask us. A plan may be pending, offered under a different name, or replaced by another option.
Find the right mix for your state
Every training partner's situation is different. We'll show you what's available in your state and help you stack coverage that fits how you train and compete.
Learn more about injury plans for martial artists →
Email info@jiujitsuinsurance.com or call (224) 505-1888.
Product availability is subject to change. Please double-check product availability by state, and ask your broker for the most up-to-date product brochure along with your quote. Prices shown are estimates only and vary by state, age, plan design and benefit level. This article is general information based on sample carrier materials. It is not a contract, a quote or a guarantee of benefits, and the policy or certificate issued in your state governs all benefits, limitations and exclusions.